During September 2026, both the EU Carbon Border Adjustment Mechanism (EU CBAM) and the forthcoming UK CBAM saw material regulatory and operational developments. Collectively, these changes signal a decisive shift from policy design into implementation readiness, with direct implications for scope, assurance expectations, and compliance planning ahead of the next phases.
EU CBAM: Changes to scope, verification and costs
1) Removal of Proposed “Emergency Brake”
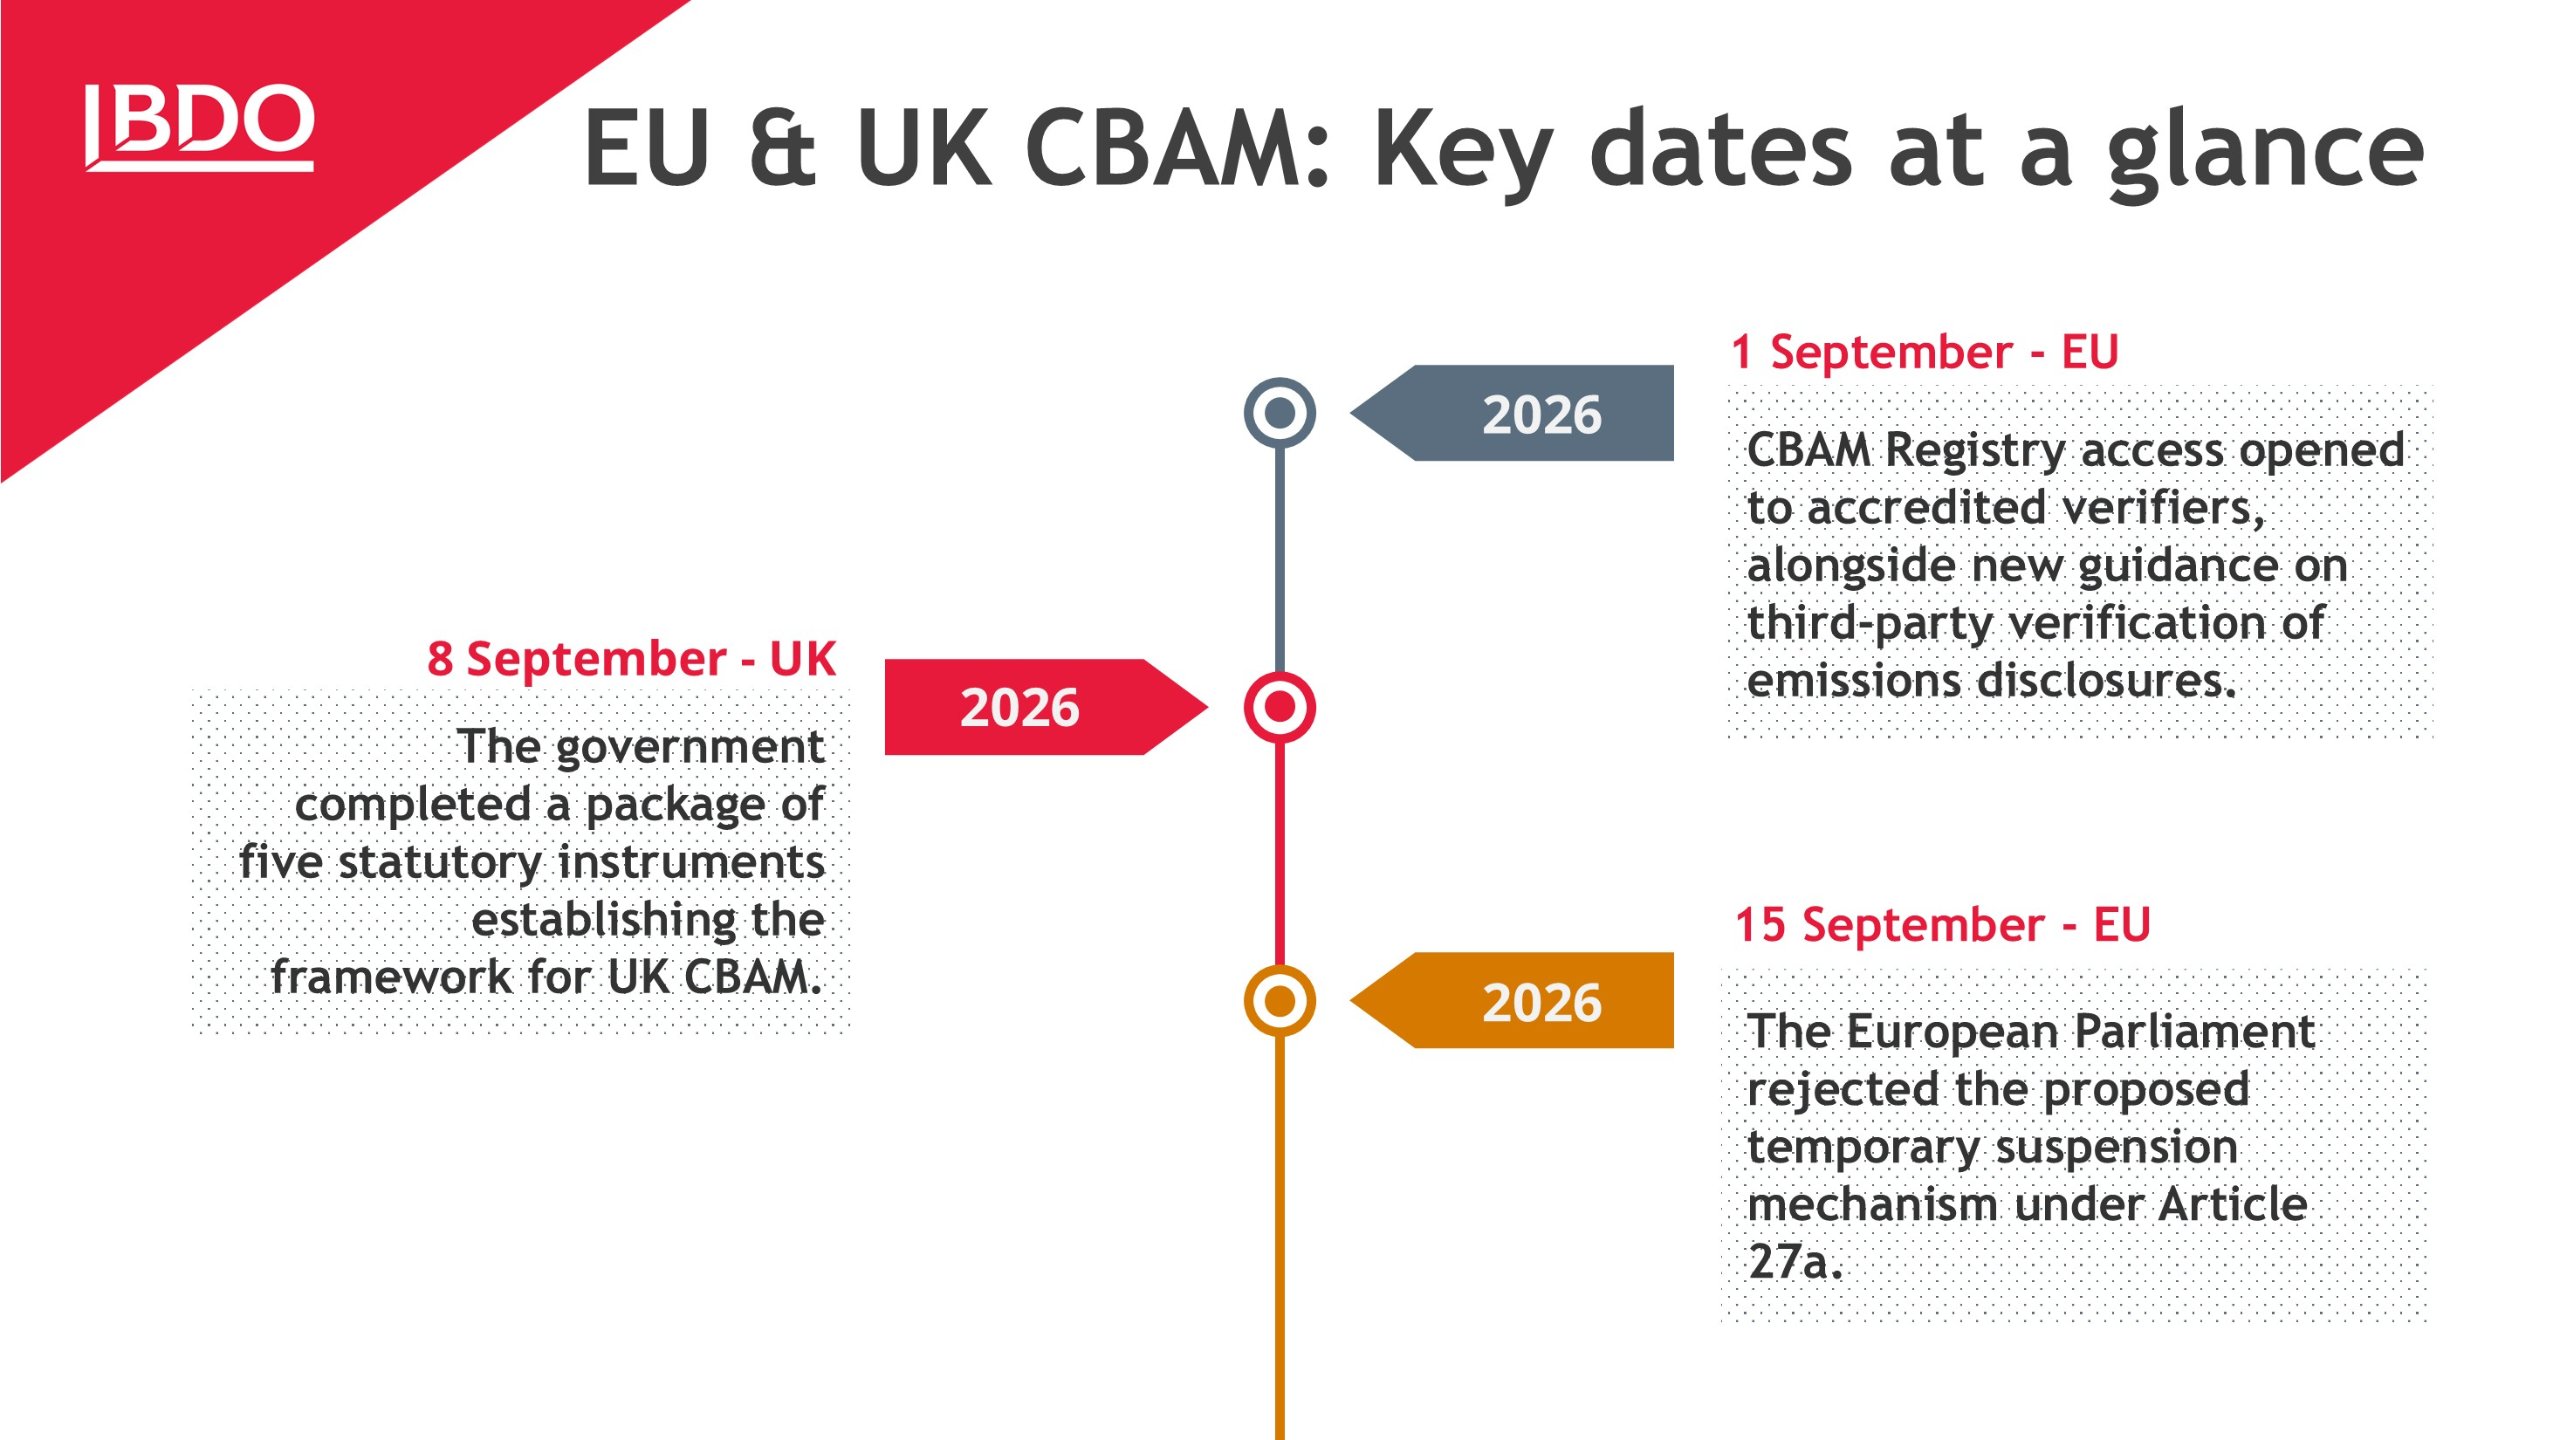
On 15 September 2026, the European Parliament voted to reject Article 27a, a proposed temporary suspension mechanism that would have allowed CBAM to be paused for certain products in the event of exceptional economic disruption or price shocks. Parliament’s position was that such a clause could reduce investment certainty and weaken incentives for decarbonisation.
2) Significant Product Scope Expansion
The Parliament also endorsed an expanded CBAM scope beyond basic materials to a much wider set of downstream steel and aluminium goods, including everyday manufactured items like fasteners, wire, springs and household articles. This matters because the carbon cost signal would move further into finished products, not just raw inputs.
Companies previously outside CBAM’s practical reach particularly those importing processed/finished steel and aluminium items—may now face new reporting and cost exposure.
3) Registry Access Opened for Accredited Verifiers & Audit Guidance Issued
From 1 September 2026, the European Commission opened CBAM Registry access to accredited verifiers. In parallel, the Commission issued detailed guidance outlining how third-party auditors will assess emissions disclosures during the first cycle of audited definitive emissions reporting.
4) Q3 CBAM Cert Price
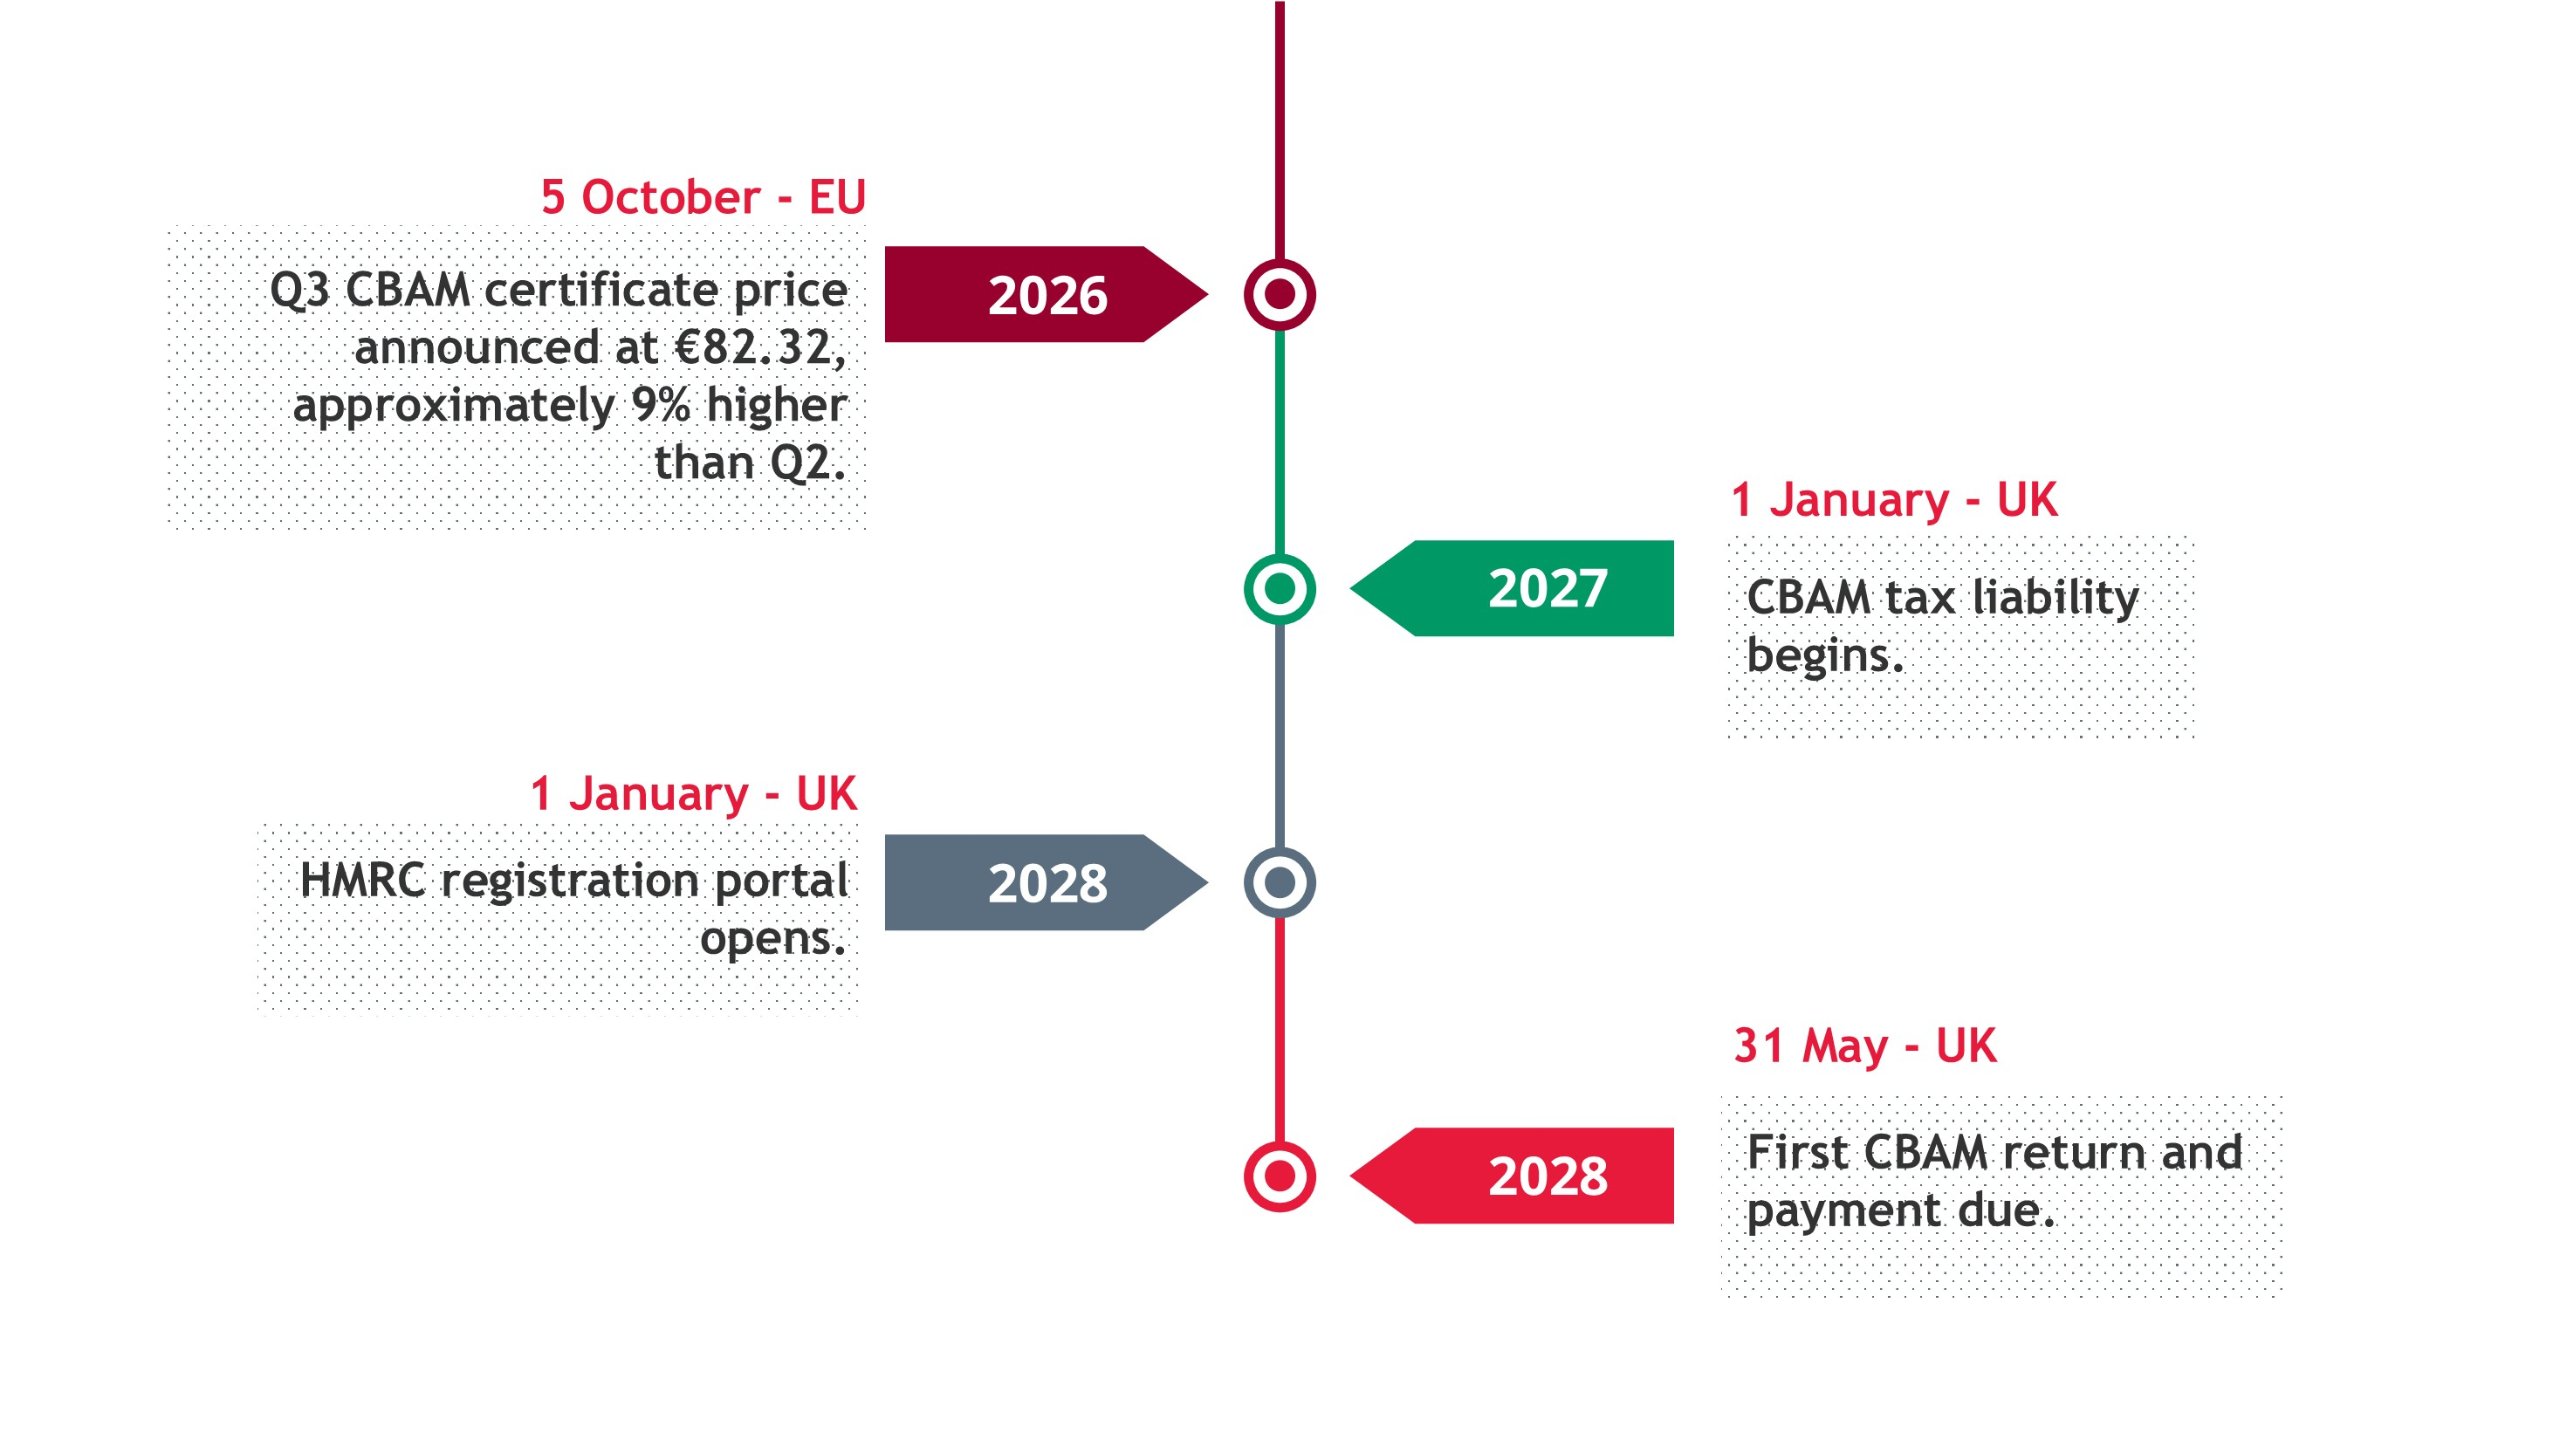
The official Carbon Border Adjustment Mechanism (CBAM) certificate price for Q3 2026 was announced on October 5, 2026 €82.32. This means the Q3 price is approximately 9% higher than in Q2, the financial impact can fluctuate considerably from one period to another. This is calculated by the weighted average of EU Emissions Trading System (EU ETS) auction clearing prices for July through September 2026. A higher carbon price means obtaining actual, verified emissions data is key as the gap between default values and actual values not cost more per tonne.
UK CBAM: Preparing for implementation in January 2027
1) Statutory Instruments Completed (Effective 1 January 2027)
On 8 September 2026, the UK government made S.I. 2026/995, completing a package of five statutory instruments under the Finance Act 2026. All five instruments are scheduled to take effect together on 1 January 2027, establishing UK CBAM tax liability from day one.
2) UK Model Reconfirmed as a Tax (Not Certificates)
September industry briefings reiterated that the UK regime will operate as a direct, self-assessed tax administered by HMRC, rather than the EU’s certificate-based mechanism.
3) Registration and Reporting Timeline Clarified
Updated guidance reaffirmed that:
- Liability begins: 1 January 2027
- HMRC registration portal opens: 1 January 2028
- First UK CBAM return and payment due: 31 May 2028